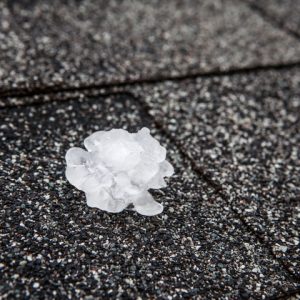
A roof insurance claim in the Kansas City area usually starts the morning after a hailstorm, with shingle granules in the gutters and a contractor at the door before the insurer has called back. The steps that follow decide how much of the repair the policy actually pays.
This guide covers how a roof insurance claim moves from the first photo to the final payment, what insurers in Missouri and Kansas are required to do, and the state rules that apply to roofing contractors on insurance work.
Start With the Policy, Not the Roof
The declarations page of a homeowners policy answers the three questions that shape every roof claim: how the roof is valued, how the deductible is calculated, and whether code upgrades are covered. Read it before the adjuster arrives.
Replacement Cost vs. Actual Cash Value
A replacement cost value (RCV) policy pays what it costs to replace the roof today. An actual cash value (ACV) policy subtracts depreciation for age and wear. On an older roof, that difference is large.
The Missouri Department of Commerce and Insurance gives the example of a 20-year-old roof destroyed by a covered loss. An RCV policy covers the full replacement. An ACV policy can pay as little as 20 percent, because the useful life of a roof is usually about 25 years.
Some policies pay RCV on the house and ACV on the roof alone. Some insurers also restrict roof coverage based on age, condition, or the number of roofing layers. The department’s Raising the Roof on Insurance Coverage tool compares roof coverage terms for the 20 largest homeowners insurers in Missouri.
How the Deductible Works
The deductible is subtracted from the claim payment. It is either a flat dollar amount or a percentage of the dwelling coverage, listed as Coverage A. Some policies carry a separate wind and hail deductible set as a percentage. On a home insured for $300,000, a 1 percent wind and hail deductible is $3,000, and a 2 percent deductible is $6,000.
When the repair cost is close to the deductible, a claim pays little or nothing. A roof inspection before filing shows whether the damage is large enough to justify a claim.
Ordinance or Law Coverage
A roof replaced today has to meet the current building code, not the code in place when the house was built. In Kansas City, Missouri, the adopted code requires ice and water shield on residential roofs.
Ordinance or law coverage, also called code upgrade coverage, pays for work the code requires that the original roof did not have. Without it, the policy pays to restore what was there before, and code-required items become an out-of-pocket cost.
The Roof Insurance Claim Process, Step by Step
1. Document the Damage and Prevent More of It
Photograph the roof from the ground, along with gutters, downspouts, siding, window screens, and any interior water stains. Write down the date and time of the storm.
The Kansas Insurance Department advises making temporary repairs, such as a tarp, to protect the home from further damage, photographing the damage before and after, and keeping every receipt. It also warns that permanent repairs made before the insurer inspects can lead to a denied claim.
2. Report the Claim
Contact the agent or the insurer’s claims line with the date of loss. Ask which forms the insurer needs and whether a signed proof of loss is required. Policies require prompt notice of a loss, so check the policy for its exact reporting terms.
3. Get an Independent Roof Inspection
A storm damage roof inspection from a roofing contractor documents hail and wind damage with photos, measurements, and a written repair estimate. That record gives the homeowner a detailed reference to compare against the adjuster’s findings.
4. Meet the Adjuster
The insurer sends an adjuster to inspect the roof and write an estimate. The homeowner can have the roofing contractor on site to point out damage and confirm measurements.
In Missouri, the contractor’s role stops there. State law prohibits a contractor from representing or negotiating on the homeowner’s behalf on the insurance claim. Coverage questions and the settlement amount stay between the homeowner and the insurer.
5. Review the Estimate and the First Payment
The adjuster’s estimate lists each line item: tear-off, underlayment, shingles, flashing, vents, and labor. Compare it line by line with the contractor’s estimate and ask the insurer about any item that is missing.
On an RCV policy, the first check usually covers the actual cash value minus the deductible. The insurer holds back the depreciation until the work is done. If the home has a mortgage, the lender is often named on the check.
6. Complete Repairs and Recover Depreciation
The held-back amount is called recoverable depreciation. The insurer releases it after the work is finished and it receives the final invoice.
Most policies set a deadline for completing repairs, often 180 days or one year from the date of loss. Missing that deadline can forfeit the depreciation payment. Scope matters as well: downgrading materials or reducing the scope of a roof replacement can lower the final payment.
7. Submit a Supplement for Hidden Damage
Some damage only shows up during tear-off, such as rotted or broken roof decking under the shingles. The contractor photographs and documents it, and the homeowner submits a supplement: a request for the insurer to review the added cost.
Insurer Deadlines in Missouri and Kansas
Missouri sets claim handling timelines in 20 CSR 100-1. For a homeowners claim, the insurer must:
- Acknowledge the claim within 10 working days of receiving notice.
- Complete its investigation within 30 days of notice, unless the investigation cannot reasonably be completed in that time.
- Accept or deny the claim within 15 working days of receiving a properly executed proof of loss.
- If it needs more time, notify the homeowner within those 15 working days with the reasons, then send a status update every 45 days.
Kansas sets its claim handling standards in K.A.R. 40-1-34. The Kansas Insurance Department’s homeowners checklist states that an insurer has 30 days to complete an investigation of a claim.
A homeowner who believes a claim is being handled improperly can file a complaint with the Missouri Department of Commerce and Insurance or the Kansas Insurance Department, depending on where the home is located.
Contractor Rules on Insurance Roofing Jobs
Missouri: RSMo 407.725
Missouri law sets specific rules for contractors doing roof and exterior work paid through an insurance claim, on residential and commercial property:
- A contractor cannot advertise or promise to pay or rebate any part of the deductible.
- Before signing, the contractor must give the homeowner written notice of the right to cancel. The homeowner can cancel before midnight on the fifth business day after receiving written notice from the insurer that all or part of the claim is not covered.
- After a cancellation, payments are returned within 10 business days, except for certain emergency work already performed.
- A contractor cannot represent or negotiate on the owner’s behalf on the insurance claim.
A violation is treated as an unfair practice under the Missouri Merchandising Practices Act.
Kansas: Roofing Contractor Registration
With few exceptions, Kansas requires roofing contractors to hold a registration certificate from the Kansas Attorney General to solicit or perform residential or commercial roofing work for a fee. Ask for the registration number and confirm the company shows In Good Standing in the Attorney General’s roofing registration directory before signing.
On either side of the state line, an offer to cover the deductible is a warning sign. The invoice the insurer sees no longer reflects the real cost of the work.
Permits in Kansas City, Missouri
In Kansas City, Missouri, replacing the roofing material, underlayment, and up to 32 square feet of roof decking does not require a permit. Replacing more than 32 square feet of decking requires a building permit and a contractor with a current KCMO business license. Repairs to rafters or other structural members add plan review and a residential contractor license. Johnson County cities such as Overland Park and Olathe set their own requirements.
Mistakes That Reduce a Roof Claim Payment
- Making permanent repairs before the adjuster inspects the roof.
- Signing with a contractor who pressures for a signature on the spot or asks the homeowner to sign over claim benefits.
- Accepting an offer to waive or rebate the deductible.
- Missing the policy deadline for finishing repairs and claiming depreciation.
- Approving lower-grade materials or a reduced scope without checking how it changes the depreciation payment.
- Filing without knowing whether the policy pays RCV or ACV on the roof.
Key Points Before Filing a Roof Insurance Claim
- Read the declarations page first: RCV or ACV, deductible type, and ordinance or law coverage.
- Document the damage, make temporary repairs only, and report the claim promptly.
- Missouri insurers must acknowledge a claim within 10 working days and decide within 15 working days of a proof of loss.
- Missouri contractors cannot rebate the deductible or negotiate the claim. Kansas roofers must be registered with the Attorney General.
- Finish repairs before the policy deadline to recover held-back depreciation.
For roof repair and replacement work anywhere in the metro, see residential roofing services in Kansas City.
Storm Damage on Your Roof? We provide free roof inspections across the Kansas City metro, document hail and wind damage with photos and measurements, and complete the repair or replacement once your claim is settled. A.I. Building Solutions is veteran-owned and GAF Commercial certified. Call (816) 835-2094 or |